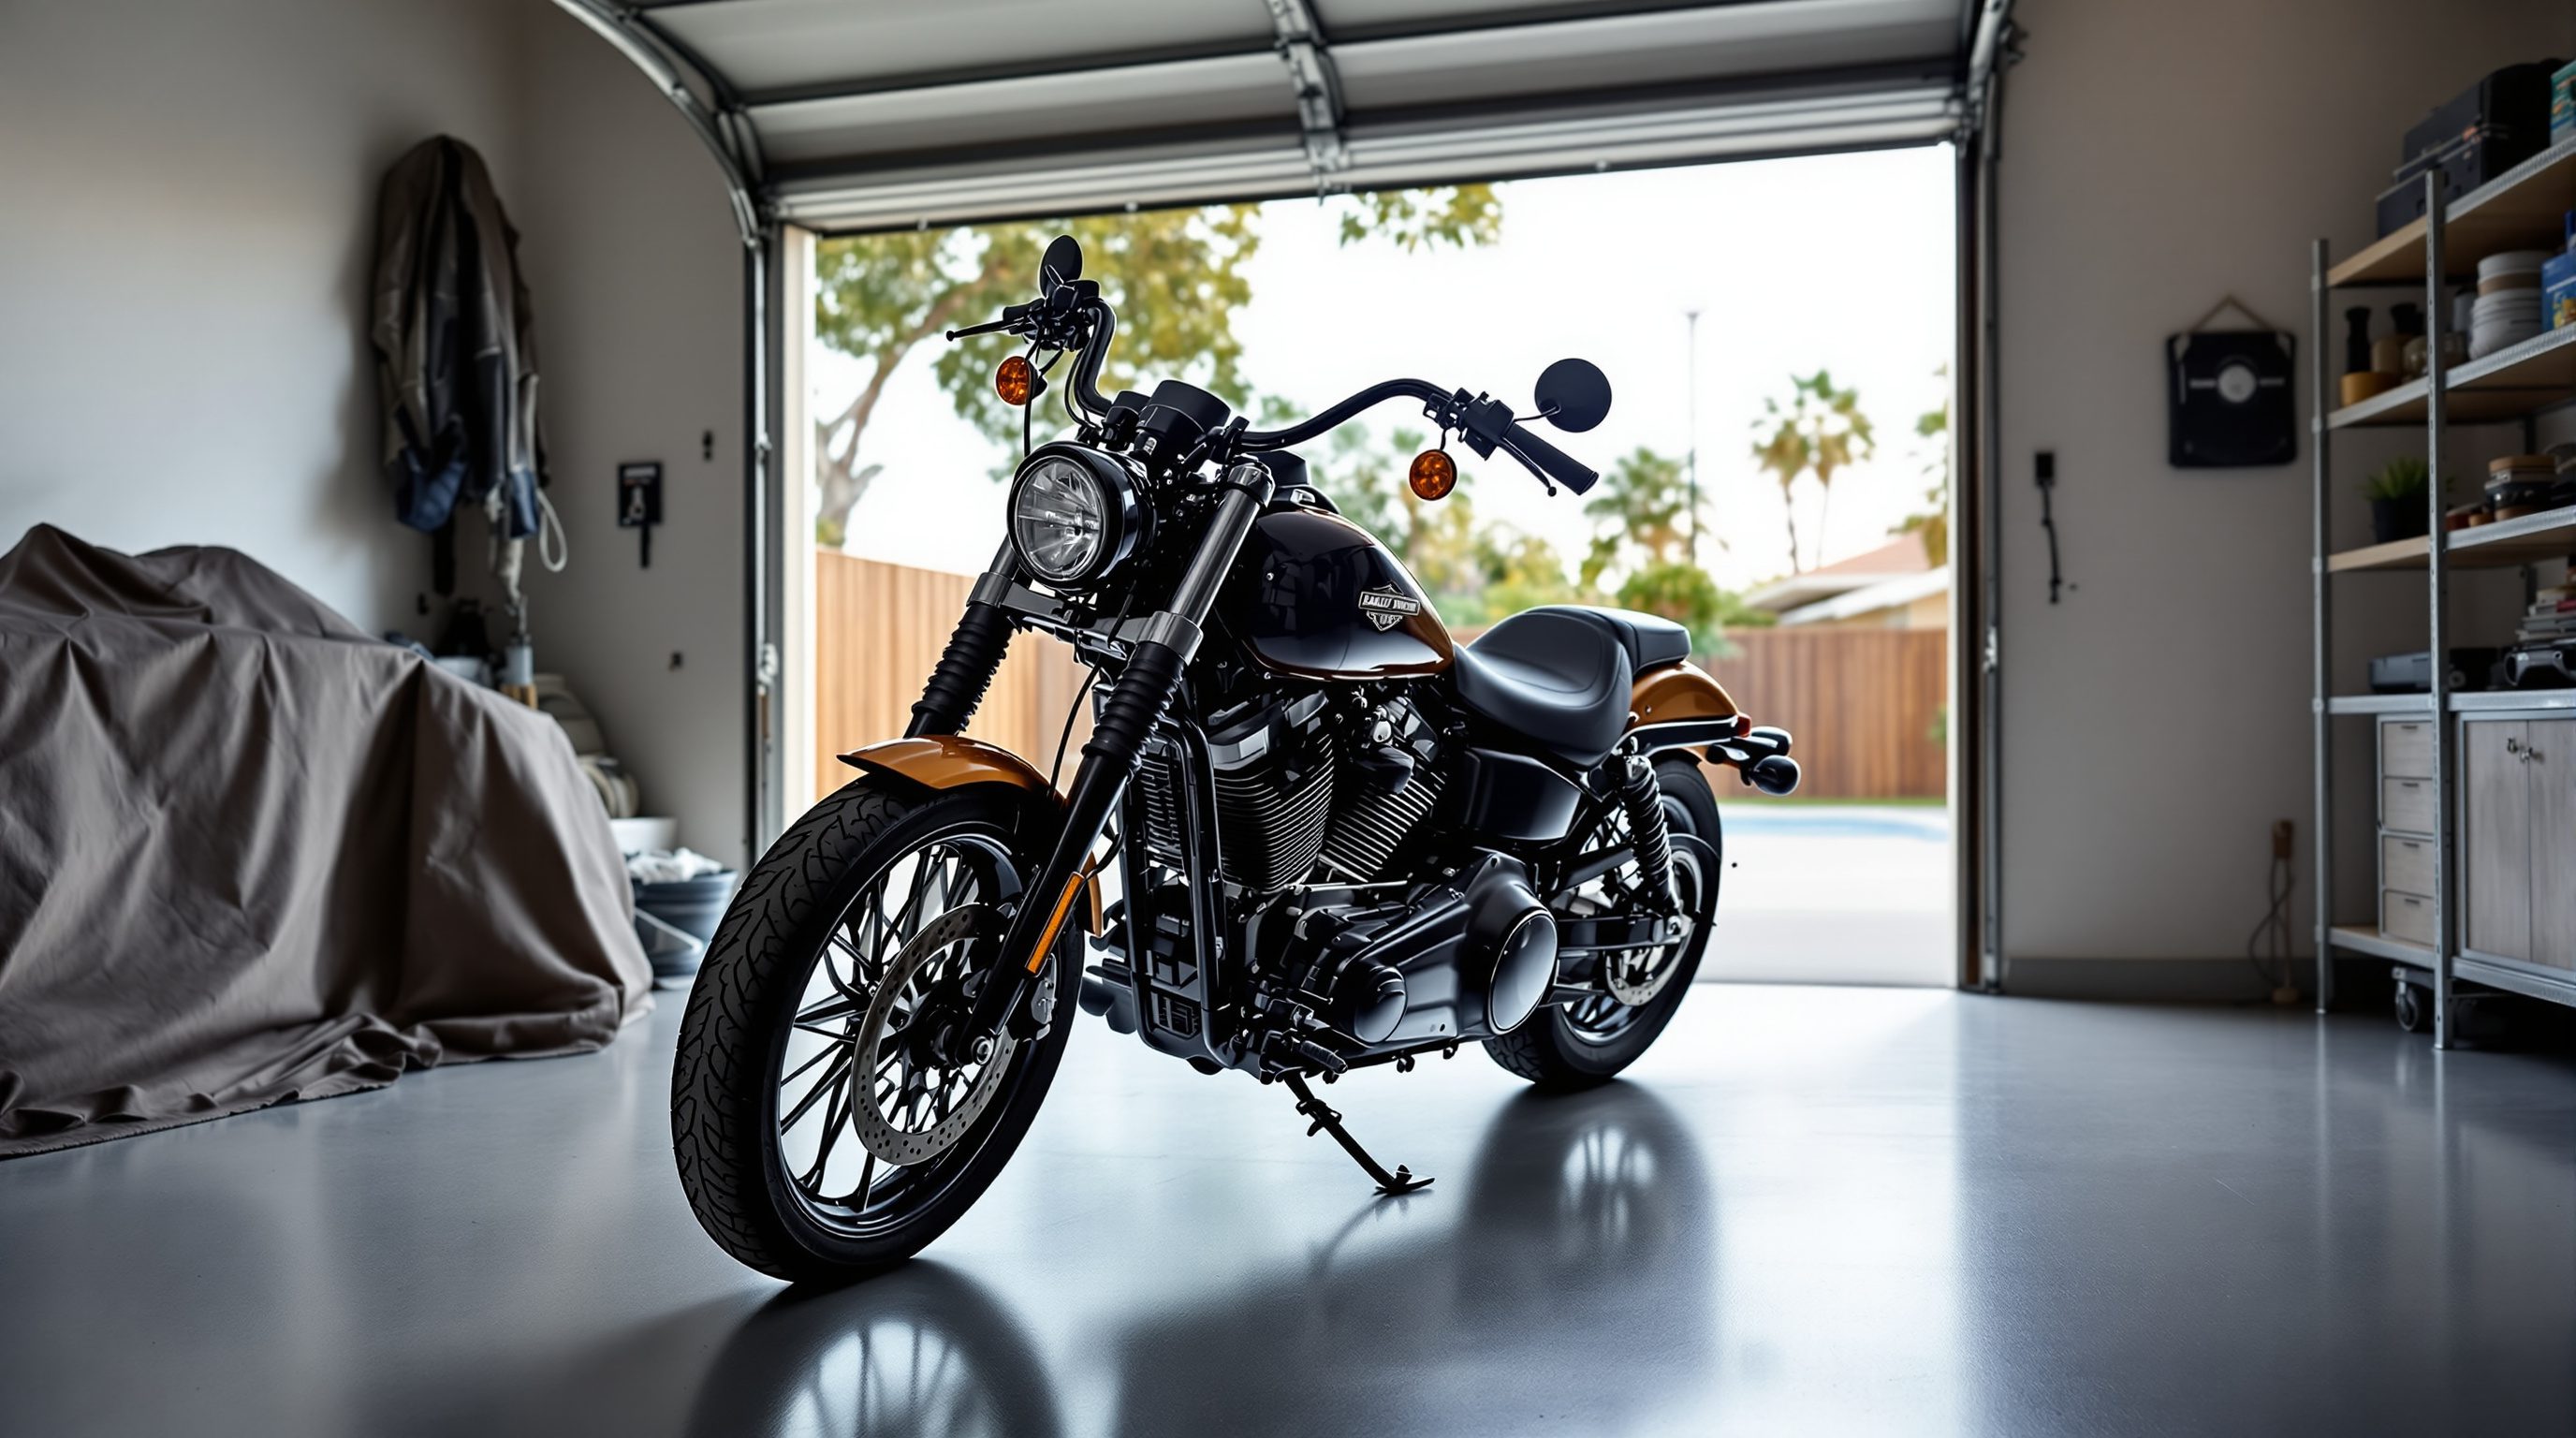
Storing Your Motorcycle for the California Winter? Do Not Cancel the Policy
Plenty of San Diego riders never really put the bike away. But when the marine layer sets in and the first storms roll through, some of us park the cruiser in the garage for a few weeks and wait out the wet roads. Nothing wrong with that. The mistake riders make is treating a stored bike like a canceled bike, calling the insurer and dropping coverage to save a few dollars while it sits. That one call can cost you far more than it saves, both if something happens to the bike in storage and when you go to reinsure in the spring. Here is how to trim your policy the smart way for a SoCal layup, and how to prep the bike so it starts right when the roads dry out.
A Parked Bike Is Still at Risk
Cutting liability the day you stop riding sounds logical, since a bike in the garage cannot rear-end anyone. But liability is not the coverage that protects the bike itself, and a stored motorcycle is exposed to plenty.
Bikes get stolen out of garages. Garages catch fire. A winter storm can flood a low garage, a tree can come through the roof, and rodents love to nest in a machine that sits untouched for weeks and chew through the wiring. Comprehensive coverage is what pays for theft, fire, water, and critter damage while the bike is not being ridden. Drop it to save money and you are betting the whole value of the bike that nothing goes wrong during the exact window it is sitting and unwatched.
Why a Coverage Gap Costs You Later
Here is the part riders do not see coming. When you cancel a policy and leave a gap, insurers do not forget. The next time you buy coverage you are treated as a lapsed driver, which usually means a higher rate, and you lose the continuous-coverage credit that rewarded you for never letting the policy drop.
So the couple hundred dollars you saved over the rainy weeks can come back as a new-policy penalty that follows you into the next term and beyond. A short gap on paper is rarely worth what it does to your rate when you reinsure in spring.
Trim Smart, Do Not Drop Everything
The move is not to cancel, it is to adjust. Call your insurer and ask about a storage or layup option, or drop to comprehensive-only while the bike is parked. You keep the coverage that matters for a bike that is not moving, you keep your policy continuous, and you cut the cost of the coverages tied to actually riding.
Think twice before you strip UM and UIM, too. San Diego winters are mild, and a dry, sunny January afternoon tempts a lot of riders back out for a quick loop. The day you pull the bike out for that ride is exactly the day you want your uninsured and underinsured motorist coverage still in force, because a driver with no coverage does not care that you only meant to ride for an hour. Talk to your insurer before you make any change, and make sure you understand what a layup endorsement does and does not cover.
Prepping the Bike for a SoCal Layup
A few weeks off is not long, but a little prep keeps the bike healthy and makes sure your coverage is squared away before you walk away from it.
- ✓ Battery. Put it on a tender or trickle charger, or pull it and keep it somewhere dry. Cold and disuse drain a battery fast.
- ✓ Fuel. Fill the tank and add a stabilizer. A full tank and stabilizer fight condensation and keep ethanol gunk from clogging the fuel system.
- ✓ Tires. Inflate to spec and move the bike, or put it on stands, so the tires do not flat-spot sitting on cold concrete.
- ✓ Moisture and critters. Cover the bike, block the exhaust, and keep rodents out so they cannot nest in it and chew the wiring.
- ✓ Coverage. Confirm your comprehensive is still active before you close the garage, so a theft or a leaking roof during the layup is actually covered.
Maxwell Agha and the San Diego motorcycle injury attorneys at Banker's Hill Law Firm represent riders hurt by negligent drivers. If you have questions after a crash, their team is here to help.