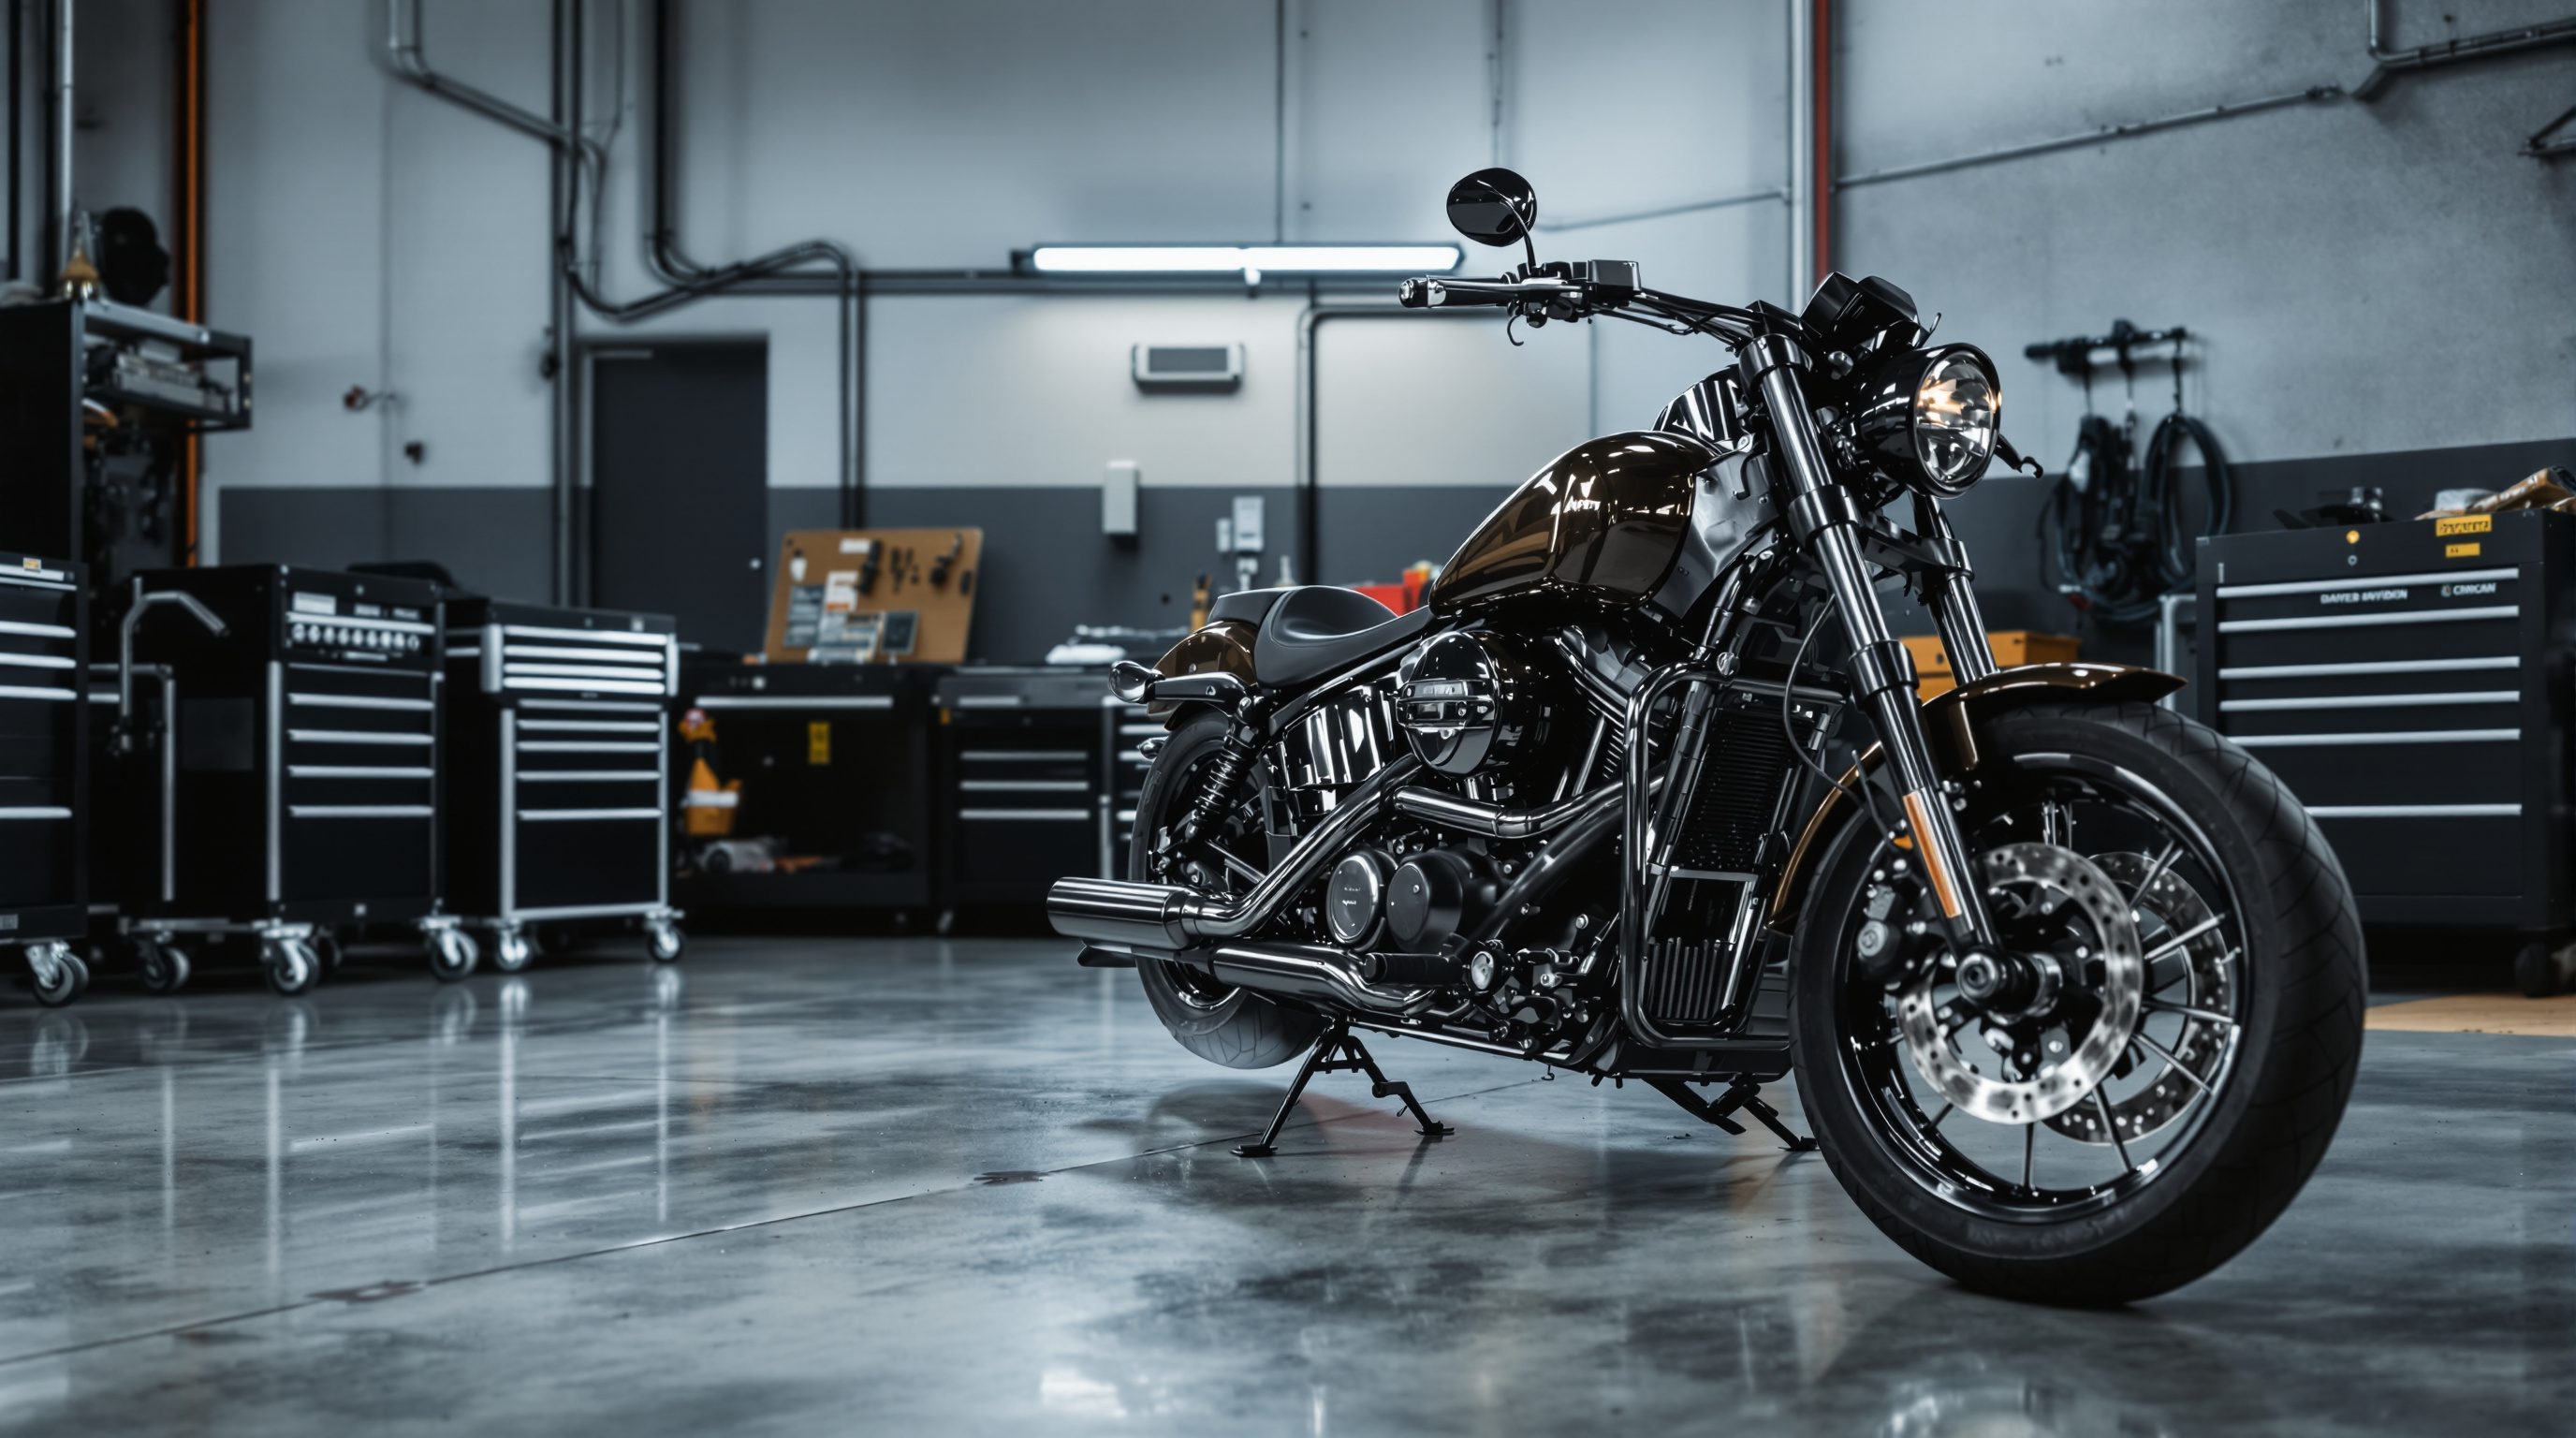
When the Insurer Totals Your Motorcycle: California Value Fights
You put real money and real weekends into your bike, and then a driver on CA-163 or I-805 wrecks it in seconds. A week later the insurer calls it a total loss and floats a number that feels like an insult. That first offer is rarely what the motorcycle is actually worth, and in California you have more tools to push back than most riders realize. This is your first-party property claim, and it is separate from your injury claim. Your injuries, your pain, and your lost wages run on their own track. The bike is its own fight over a single question: what was it worth the moment before the crash. Here is how California handles that.
How a Total Loss Gets Declared
An insurer totals a motorcycle when the cost to repair it, often combined with the salvage value, crosses a threshold against the bike's value. California uses a total-loss formula rather than a fixed percentage, so there is no single magic number like some states use. What matters for your wallet is the other half of the equation: the actual cash value, or ACV, they assign to your bike. Every dollar they shave off that value is a dollar out of your payout, so the ACV is where the real fight lives.
Actual Cash Value Is Where They Lowball You
Actual cash value is supposed to be what your motorcycle was worth right before the crash, given its year, mileage, condition, and equipment. The insurer builds that number from comparable sales and valuation reports, and those reports routinely understate a well-kept bike.
They may compare your machine to neglected examples, ignore low mileage, or leave out money you sank into it. That is why documenting the bike is the single most valuable thing you can do.
- ✓ Recent photos.. Clean shots of the whole bike and the odometer from before the crash prove condition and mileage.
- ✓ Upgrades and accessories.. Exhaust, bags, tires, stereo, and custom work add value, so list every part with receipts.
- ✓ Service records.. A maintenance history shows the bike was cared for, not run into the ground.
- ✓ Your own comps.. Pull local listings for the same year, model, and mileage to counter their low comparables.
- ✓ The valuation report.. Ask for the exact report behind their number and check every comp and adjustment for errors.
California Requires Sales Tax and Fees in the Payout
Here is the rule a lot of riders never hear: in California, a total-loss settlement is not just the bare value of the bike. The insurer is required to include sales tax and the associated fees in what they pay you, because replacing your motorcycle means paying those costs again. If the offer in front of you is only the vehicle value with no line for tax and fees, that offer is short. Do not sign off on a number until you see that those amounts are built in, and treat their absence as a sign the whole offer deserves a hard second look.
Getting to a Fair Number
You are not stuck with the first figure. Actual cash value is negotiable, and the way you move it is with evidence, not argument. Send the insurer your photos, your upgrade receipts, your service history, and your own comparable listings, and make them justify every adjustment on their valuation report. When their comps are worse bikes than yours, say so in writing and show why. If the gap stays wide, your policy may have an appraisal process, and a serious dispute is worth running past an attorney, especially when the property fight is tangled up with an injury claim.
Do Not Forget the Loan Gap
If you still owe on the motorcycle, the ACV can come in below your loan balance, and you are left owing money on a bike you no longer have. Gap coverage, if you bought it, pays that difference. Without it, that shortfall is yours, which is one more reason not to accept a soft ACV. Squeezing the value up also shrinks any gap you would otherwise eat.
Keep the Property and Injury Claims Straight
Settling the bike does not settle your body. Insurers sometimes push a quick property payout with paperwork that also releases your injury claim, so read anything before you sign and never let a check for the motorcycle close the door on your medical claim. California generally gives you two years to bring a personal injury lawsuit (Code of Civil Procedure 335.1). The property side runs on its own contract deadlines, so keep the two straight and do not let a fast bike check cost you the bigger claim.
Led by Maxwell Agha, Banker's Hill Law Firm in San Diego fights for injured motorcyclists. Reach out to their San Diego motorcycle accident attorneys anytime you need real answers.