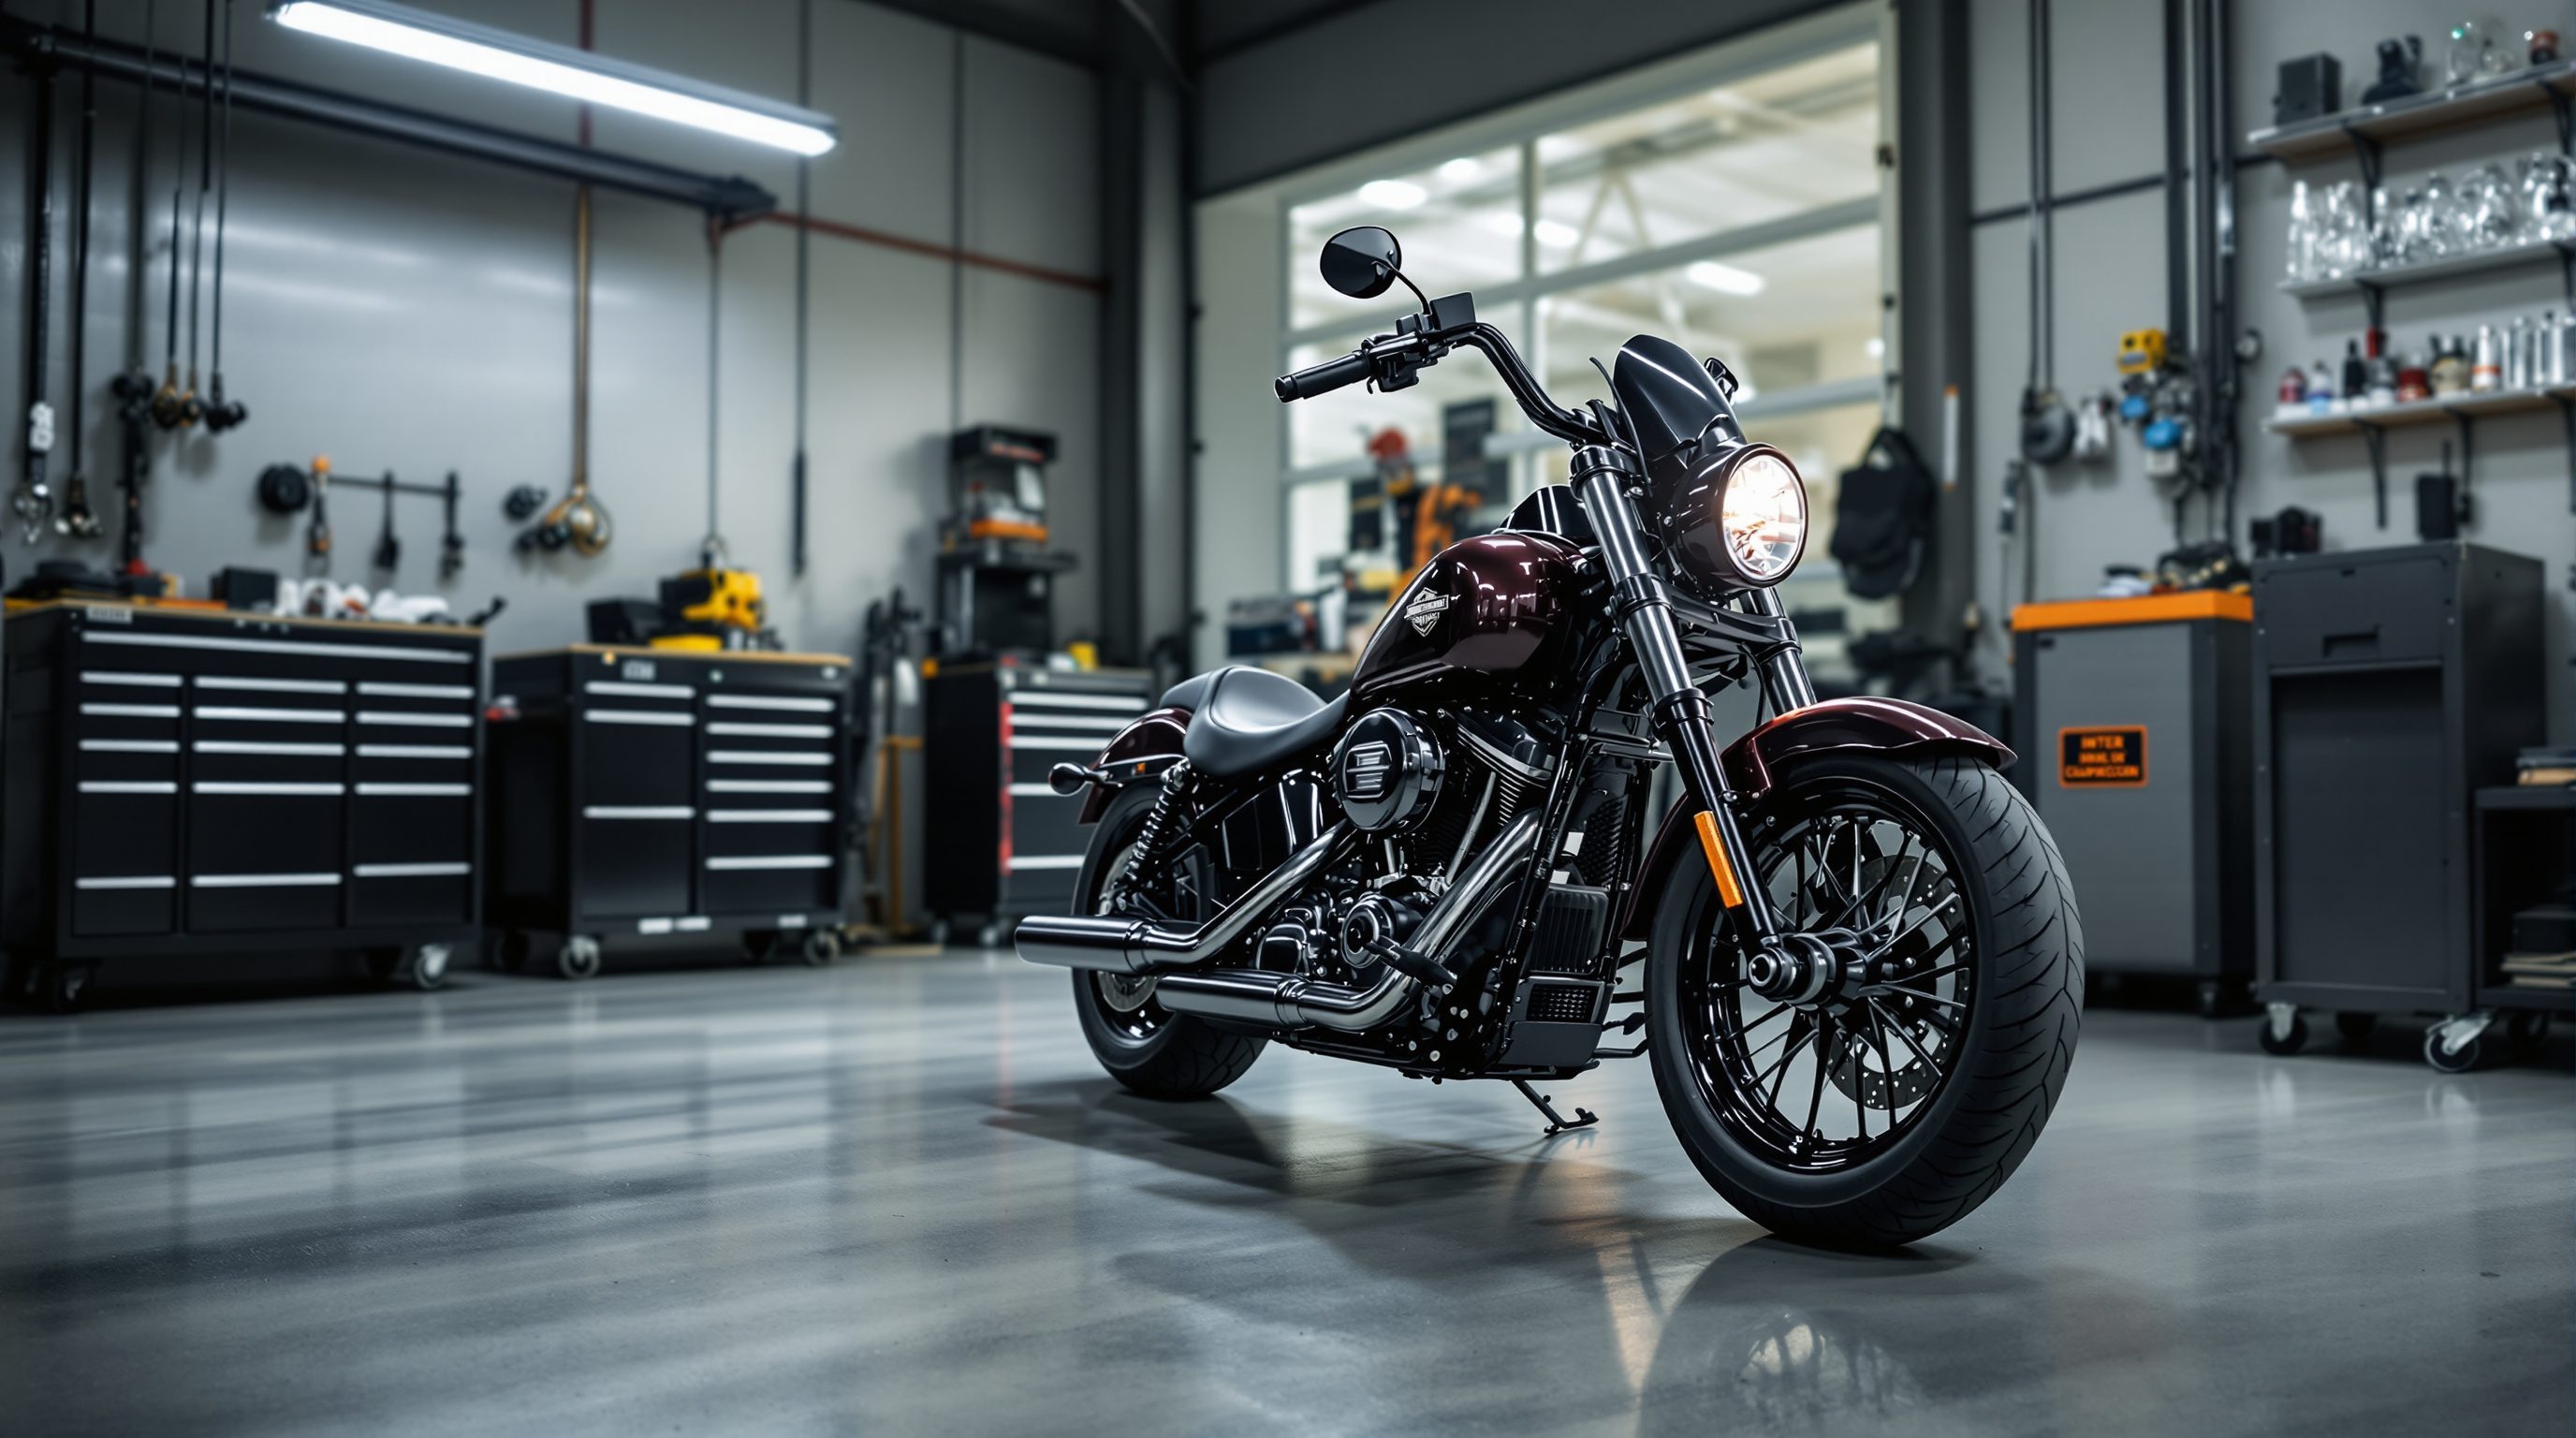
Total Loss: How DMV Insurers Value Your Wrecked Motorcycle
You did not just lose a vehicle. You lost the bike you spent the season on, from Skyline Drive and the Blue Ridge to Great Falls, Sugarloaf Mountain, and the run out to Harpers Ferry. Then the adjuster calls with a number that feels like an insult. When a motorcycle is a total loss, the insurer does not pay what you paid, what you would pay to replace it, or what the bike means to you. It pays what it calls actual cash value, and the gap between their number and the real one can run into the thousands. To make it messier, the total-loss and tax rules are not the same in DC, Maryland, and Virginia. Here is how DMV insurers value a wrecked bike, where they cut corners, and how to push back on a lowball.
What Actual Cash Value Really Means
Actual cash value, or ACV, is what a comparable bike would sell for in your area right before the crash. It is not the sticker price and not a replacement cost. It is a market estimate, and the insurer's vendor builds it from a database of comparable sales and listings.
When a bike is totaled depends on where you are. DC, Maryland, and Virginia each have their own way of deciding when a vehicle crosses into total-loss and salvage territory, whether by a set percentage of value or a repair-cost formula, and the thresholds differ. On a motorcycle the line gets crossed fast. A bent fork, a cracked frame, and damaged bodywork can total a bike that felt like it only slid a few feet.
Your Property Claim Is Separate from Your Injury Claim
Keep these two apart in your head from day one. The totaled-bike claim is a first-party property claim about the value of the motorcycle. If you were hurt, the injury claim is a separate matter, and in the DMV it runs into contributory negligence: if you are found even 1 percent at fault, you can be barred from recovering on the injury side entirely. Never let an insurer bundle a property settlement with a release of your injury claim, and do not sign a broad release to get the bike paid out.
How Insurers Lowball the Number
The value report is not gospel. It is an opening offer, and the details are where the money hides. Watch for these moves.
- ✓ Wrong comps.. They use bikes with higher mileage, worse condition, a different trim, or from a different market, when yours was clean and low miles.
- ✓ Condition markdowns.. They knock the value down for wear you do not think you had, with no photos to back it up.
- ✓ Ignored upgrades.. Aftermarket exhausts, saddlebags, windshields, custom paint, and performance parts get left out or undervalued.
- ✓ Taxes and fees.. Whether sales tax and title and registration fees get added into a total-loss payment can vary by jurisdiction and policy, so check that yours are handled correctly.
- ✓ Slow timelines.. Delays push you toward taking the first offer just to be done.
Build Your Own Case for Value
You do not have to accept their number. Pull together your own comps: recent sales and dealer listings for the same year, make, model, trim, and similar mileage across the DC metro. Local pricing may differ from a national database. Then document what you did to the bike. Keep receipts for tires, service, and upgrades, and send photos from before the crash, since your phone is full of shots of the bike on Skyline Drive or along the Potomac. Documented condition is the best defense against a condition markdown.
Aftermarket Parts and Your Riding Gear
Insurers often ignore aftermarket parts unless you prove them. Send an itemized list with receipts and photos. If a part was bolted on, it can be part of the bike's value, but custom work you cannot document is work they will not pay for.
Your gear is a separate issue. Helmet, jacket, gloves, boots, and electronics were damaged in the crash and are personal property, not part of the bike's ACV. In a liability claim against an at-fault driver, replacement of damaged gear is generally something you can claim, so keep the helmet and everything else you wore, and do not throw it away.
Disputing the Offer, Salvage Titles, and Gap
Reject the first offer in writing and send your comps and records. Many policies also have an appraisal clause that lets each side name an appraiser, which is an option if you hit a wall. If you keep the bike, expect it to carry a salvage designation, which can make it hard to insure and register and cuts resale value, and the salvage-title rules differ across DC, Maryland, and Virginia. Ask about the salvage deduction before you decide. If you owe more on the loan than the ACV, gap insurance or a loan payoff rider can cover the difference, so check your policy and your finance contract right away.
Led by Seann Malloy, Malloy Law Firm in Washington DC metro fights for injured motorcyclists. Reach out to their Washington DC metro motorcycle accident attorneys anytime you need real answers.