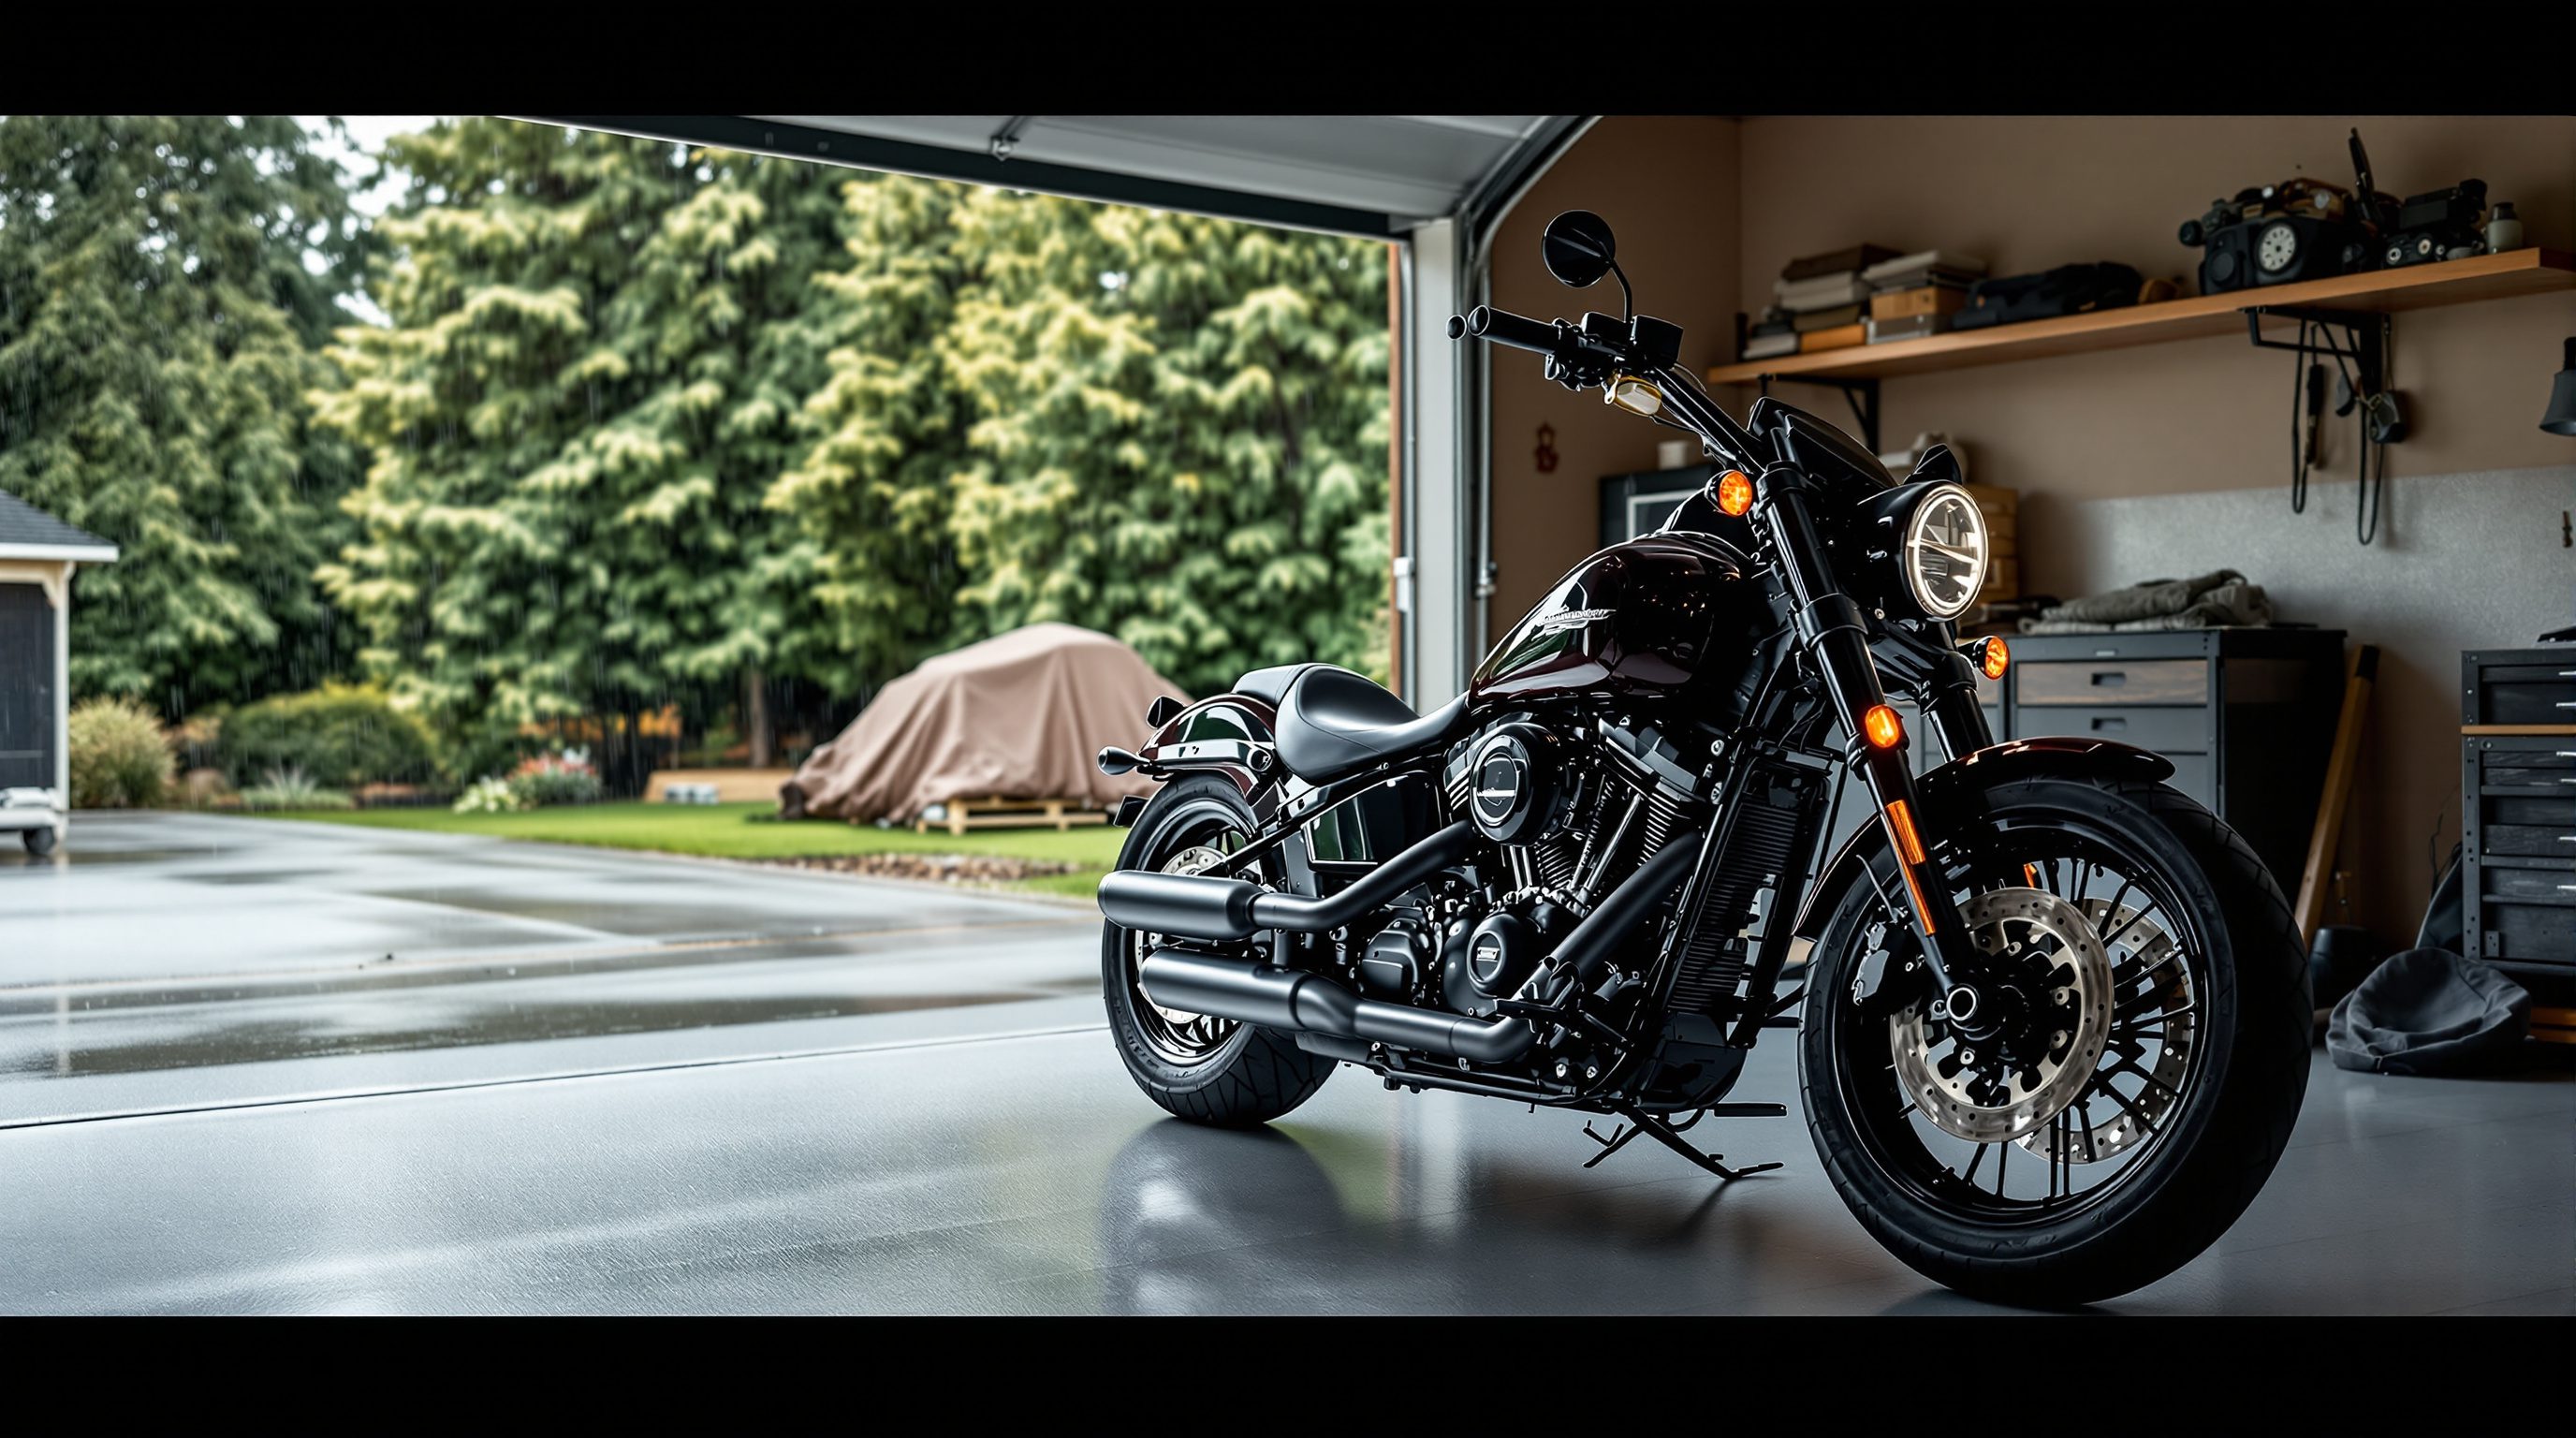
Winter Storage and Your Motorcycle Insurance in Washington: Should You Drop Coverage?
Every Puget Sound rider knows the drill. Somewhere around the holidays the rain settles in for good, the roads stay dark and greasy, the passes ice over, and the bike goes under a cover until the days grow back. Right about then the renewal notice shows up, and stripping the policy down to save a few dollars while the machine just sits looks like an easy win. In western Washington, that math is a trap. The months your motorcycle is parked are exactly the months a winter storm, a flood, a fallen limb, or a thief can total it, and how you handle the policy over the wet season follows you straight into your spring rate.
A parked bike is not a safe bike
A bike in the garage is not out of danger just because it is not moving. A Northwest winter still throws windstorms off the Pacific, saturated ground and localized flooding, heavy wet snow when the cold slides to the lowlands, and long dark weeks that make a quiet garage or carport an easy target. A tree limb through the roof in a Puget Sound blow, a flooded garage, a power-out night, or a break-in while the neighborhood is asleep does not care that you were not riding. The one coverage that pays for all of that is comprehensive, and it is also the cheapest part of your policy. Dropping it to save a small amount over a few idle months is how riders end up eating the full loss of a stored bike out of pocket.
What comprehensive actually covers while your bike sits
Comprehensive is the storage rider's coverage. It handles the damage that has nothing to do with a crash, which is nearly every way a parked motorcycle gets hurt through a Washington winter. Keep it in force through the whole off-season and it does the work while you wait for spring.
- ✓ Storm and flood damage. A downed limb, a windstorm, wind-driven rain, or a flooded garage that reaches your bike is comprehensive territory, not collision.
- ✓ Theft and vandalism. A stored bike is a target through the dark months, and a stolen or stripped motorcycle is only covered if comprehensive is still on the policy when it happens.
- ✓ Fire, rodents, and falling objects. Garage fires, chewed wiring over a long idle winter, and anything that falls on a parked bike are exactly what this coverage exists for.
- ✓ Keep the policy unbroken. A winter lapse pushes you into a higher risk tier and breaks your uninsured-motorist continuity, so reduce coverages if you must but never let the policy go dark.
Why a coverage lapse costs you more than it saves
The bigger mistake is not trimming a coverage, it is canceling the policy outright and letting it lapse. Insurers treat any gap as a red flag, and even a short winter lapse can push you into a higher risk tier when you restart in spring. You come back to a higher premium than you left with, and the few dollars you saved over a couple of quiet months are gone many times over. A continuous policy keeps your rate where you earned it. If money is tight, reduce coverages you truly are not using while the bike is parked, but keep the policy alive and unbroken.
The uninsured-motorist line you never cut
Here is the Washington reality that makes a lapse worse than it looks. Washington is an at-fault state, not a no-fault state, and Personal Injury Protection is optional coverage you can add or reject. After a crash you lean on your health insurance, any PIP you carry, the at-fault driver, and above all your own uninsured and underinsured motorist coverage. On roads full of drivers carrying only the bare 25/50/10 minimums, or no coverage at all, that UM and UIM coverage is your real backstop, and insurers must offer it for a reason. Cancel the policy over winter and let it lapse and you are not just risking the bike, you are breaking the continuity of the coverage that protects your body the moment you ride again in spring.
What your lienholder requires, and what you can safely trim
If the bike is financed, the choice may not even be yours. Almost every lienholder requires both comprehensive and collision for the life of the loan, parked or not, and dropping them lets the lender force-place its own far pricier coverage on you. Read the loan terms before you touch a financed bike's policy. If the bike is owned outright and genuinely will not turn a wheel until spring, ask your agent about a true storage or lay-up approach that reduces or suspends collision while keeping comprehensive and the policy itself active. The goal is to stop paying for road risk you are not taking on, without ever opening a gap, dropping the comprehensive that guards a stored bike, or breaking your uninsured-motorist protection.
Janelle Bailey and the Seattle-Tacoma motorcycle injury attorneys at Washington Injury Law represent riders hurt by negligent drivers. If you have questions after a crash, their team is here to help.